Key takeaways
- Good documentation ties together three things: where the damage is, how severe it is, and which storm caused it.
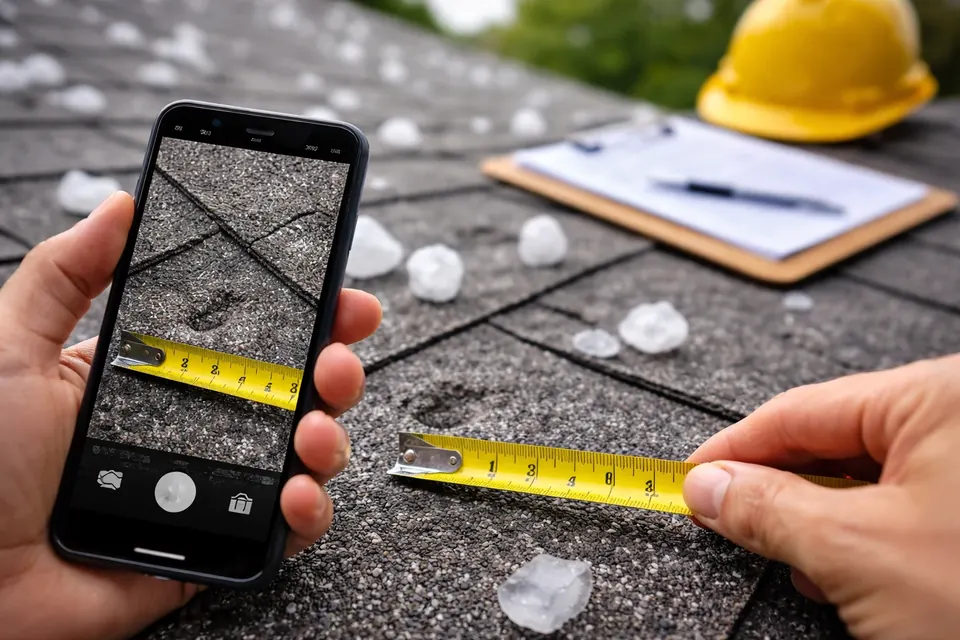
- Photograph at three distances (wide, mid-range, close-up) and include a scale reference such as a tape measure or coin.
- Soft metals like gutters, roof vents, and AC condenser fins often show the clearest hail marks and help support roof damage.
- NOAA storm reports for Dallas County can help connect your damage to a date and hail size.
- Keep everything in one organized claim file, leave original photos unedited, and log every conversation with the insurer.
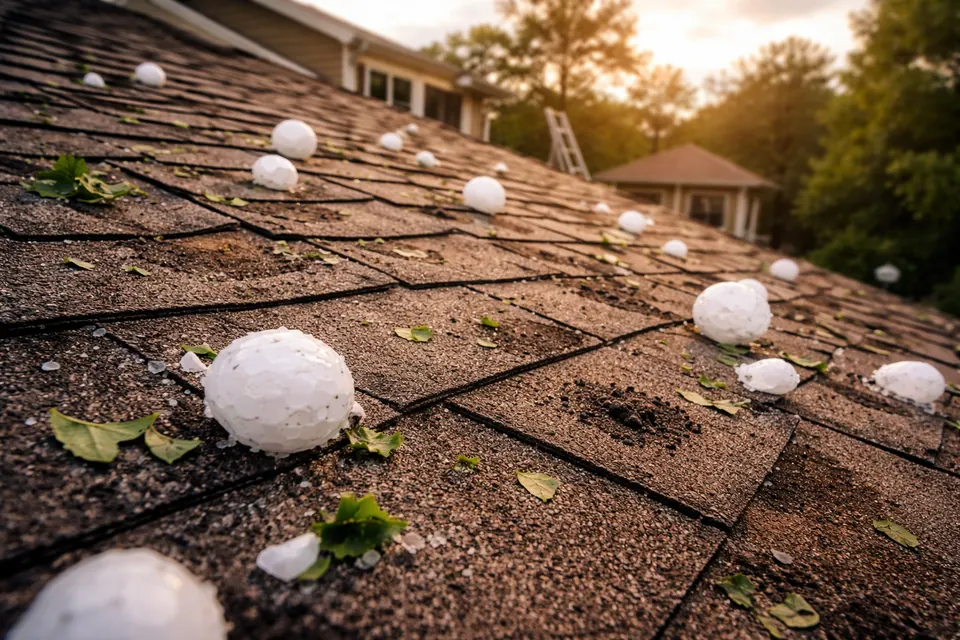
A North Texas hailstorm can be over in ten minutes. The ice melts, the sun comes out, and by the next morning it can be hard to believe anything happened. But the damage left behind on a roof, gutters, siding, and windows is often real, and the evidence starts fading right away. Knowing how to document hail damage for an insurance claim is one of the most useful skills a Dallas homeowner or business owner can have, because the insurer will decide your claim largely on what it can see and verify.
This guide gives you a practical, step-by-step method: what to look for, what tools to use, how to take photos and video that actually help, how to use public storm data, and how to organize it all so your claim is clear from day one. It applies to homes and commercial buildings in Dallas, Dallas County, and the surrounding North Texas communities.
Why hail documentation matters so much in Dallas
Dallas County is firmly in hail country. NOAA’s Storm Events Database lists 841 hail reports for the county since 1955, and 250 of them were 1.75 inches (golf ball size) or larger. Reports peak in April and May, with a long season from March through June and a smaller rise in October. Large-hail days are not rare: NOAA records include 4-inch hail near Cedar Hill on June 12, 2023, grapefruit-size hail in Irving on May 24, 2011, and 3-inch hail near Dallas Baptist University on April 25, 2026, where car windows were blown out.
Because storms are frequent, the same roof may have been hit more than once, and insurers often look closely at whether damage came from the storm you reported, an earlier storm, or normal aging. Strong documentation answers those questions before they are asked:
- It shows the damage exists and exactly where it is.
- It shows how widespread and severe it is.
- It connects the damage to a specific storm date rather than wear.
The Texas Department of Insurance’s advice after hail is straightforward: take photos and video, list the damage inside and outside, and keep damaged items until your insurer says you can throw them away.
What hail damage looks like
On the roof
- Composition (asphalt) shingles: random, roughly circular marks where granules are knocked off and the dark mat shows through; soft, bruised spots that feel spongy when pressed; cracked shingles or broken seal strips.
- Metal roofing and components: dents in panels, ridge vents, turtle vents, pipe jacks, flashing, and chimney caps. Note that some policies exclude cosmetic damage to metal roofing, so check yours.
- Tile and slate: cracks, chips, or broken corners, sometimes hairline.
- Low-slope commercial roofs (TPO, modified bitumen): punctures, fractures, or crushed insulation beneath the membrane, which may need closer inspection to confirm.
Around the exterior
- Dents in gutters, downspouts, and metal window wraps
- Torn or punctured window screens and cracked glass
- Cracked or chipped siding, trim, and paint; spatter marks on fences, decks, and outdoor furniture
- Bent fins or dents on the outdoor AC condenser
- Dents on garage doors, mailboxes, and light fixtures
Inside and hidden
- Ceiling stains, bubbling paint, or drips during later rain
- Wet or compressed attic insulation
- Water stains or daylight on the underside of the roof decking, seen from the attic
Some damage appears right away; leaks may not show up until the next heavy rain. Treat documentation as an ongoing task for the first few weeks, not a one-day job.
What you need before you start
| Item | What it is for |
|---|---|
| Smartphone or camera | Photos and video with the date and time saved in the file data |
| Tape measure or ruler | Scale in close-ups of hailstones, dents, and impact marks |
| Coin | A quick, universal size reference when a tape is awkward |
| Sidewalk chalk | Circling impacts so they show up in photos (on surfaces where it washes off) |
| Notebook or notes app | Storm details, locations of damage, and observations |
| Flashlight | Attic, closets, and dark corners |
| Binoculars or a zoom lens | Seeing the roof from the ground |
Professionals may also use drones, moisture meters, Xactimate estimating software, and Matterport 3D imaging. You do not need any of that to build a strong starting record.
Step-by-step: how to document hail damage for an insurance claim
Step 1: Put safety first
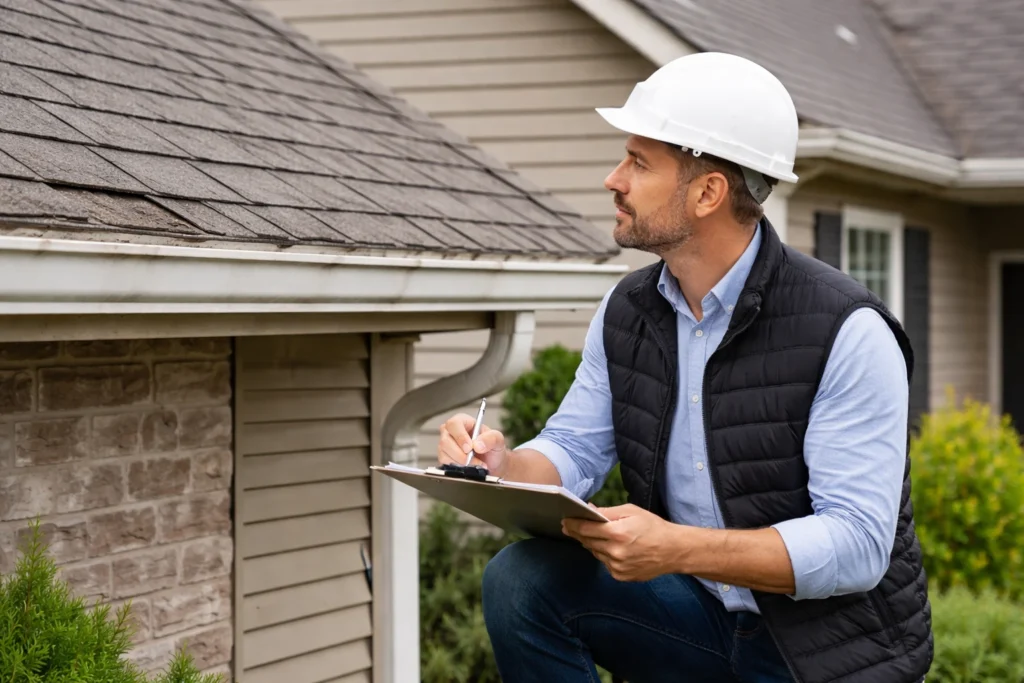
Do not climb onto a wet, steep, or damaged roof, and stay away from downed power lines. Two-story homes, steep pitches, and tile roofs are especially risky. Work from the ground and leave the roof surface to a qualified roofer or adjuster.
Step 2: Record the storm itself
Write down the date, approximate start time, how long it lasted, the largest hail you saw, and the wind direction if you noticed it. Photograph hailstones next to a ruler or coin as soon as possible, because they melt quickly. Video of hail falling or piling up in the yard is useful too.
Step 3: Shoot wide, mid-range, and close-up
- Wide: each side of the building from the street or yard, showing the roof and that elevation.
- Mid-range: each roof slope you can see, each gutter run, each window, and the AC unit, so a reviewer can tell where every close-up was taken.
- Close-up: individual impacts with a tape measure or coin for scale.
Take more photos than you think you need. Keep them sharp and evenly lit; low morning or late-afternoon sun can make dents easier to see on metal. Do not use filters or edits.
Step 4: Mark and measure
Where it is safe, circle impacts on gutters, downspouts, and siding with chalk and photograph them with a tape measure. Measuring the width of dents in soft metals gives a sense of hail size. On roofs, professionals often mark a test square on each slope and count hits, which is one reason a qualified roof inspection matters.
Step 5: Check soft metals and the AC unit
Gutters, downspouts, roof vents, and AC condenser fins dent easily and rarely show “wear” that looks like hail. Consistent dents on these items, facing the same direction, are strong supporting evidence for damage on the roof above them.
Step 6: Document the interior and attic
Photograph any ceiling stains, wet insulation, or drips. If you can safely reach the attic, look at the underside of the decking with a flashlight. Water damage changes quickly, so photograph it promptly and again if it spreads.
Step 7: Record a narrated video walkthrough
Walk around the building slowly and describe what you see: “North side, gutter above the garage, dents about an inch wide.” State the date at the start. Video helps an adjuster understand the layout and how damage on different items relates.
Step 8: Pull the storm data
Search NOAA’s Storm Events Database for Dallas County on your storm date, and check National Weather Service Dallas/Fort Worth reports. Save a copy of any report near your address. Our storm lookup tool and Dallas storm history page make this easier. Keep in mind that a lack of reports near you does not prove hail did not fall; reports depend on someone observing and submitting them.
Step 9: Keep a written log
Note the date you discovered each piece of damage, when you reported the claim, the claim number, inspection dates, and every call or email with the insurer, including names. A simple dated note on your phone works if you keep it consistent.
Temporary repairs: document before and after
Most policies expect you to take reasonable steps to prevent further damage, such as tarping a roof or boarding a broken window. Photograph the damage first, then photograph the temporary repair, and keep every receipt. Hold off on permanent repairs until the insurer has had a chance to inspect, unless waiting would cause more damage; if so, document thoroughly and tell the insurer in writing.
Organizing your claim file
A tidy file makes it easier for an adjuster to say yes. Set up one folder, digital or paper, with:
- Photos and video: originals kept unedited, sorted by area (roof, each elevation, interior, AC, contents).
- Storm evidence: your notes, hailstone photos, and saved NOAA or NWS reports.
- Policy documents: the full policy, declarations page, and endorsements. Note your wind/hail deductible, which on many Texas policies is a percentage of the dwelling limit.
- Estimates and invoices: contractor bids, temporary repair receipts, and the insurer’s estimate when it arrives.
- Correspondence log: dates, names, and summaries of every contact.
Our claim documentation checklist lays this out in a format you can print. For roof-specific advice, see hail damage roof insurance claims.
Common documentation mistakes
- Only close-ups. Without wide and mid-range shots, no one can tell where a dent is or how widespread the damage is.
- No scale reference. A dent without a coin or tape can look smaller or ambiguous.
- Skipping soft metals. Gutters, vents, and the AC unit often provide the clearest proof.
- Waiting weeks. Fresh marks weather, and new storms can muddy the timeline.
- Editing photos. Filters and crops can raise questions; keep originals.
- Throwing away damaged items before the insurer has seen them or said it is OK.
When your documentation meets resistance
Even a well-documented claim can be underpaid or denied, often on grounds like wear and tear, pre-existing damage, or “cosmetic only.” If that happens, ask for the reasons in writing, compare the insurer’s estimate to your evidence and contractor bids, and consider a second opinion. Our guide on what to do if your hail claim was denied in Texas walks through next steps, and public adjuster vs. insurance adjuster explains who represents whom.
A public adjuster, such as Dallas Public Adjuster, can re-inspect the property, build a line-item estimate, and present the documentation to the insurer on your behalf. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. No one can guarantee the outcome, but a complete record gives your claim the best footing. Learn more on our Dallas hail damage claims page.
Final thoughts
Hail damage rarely looks dramatic, but it can be costly. The owners who come through the claims process with the least frustration tend to document early, document thoroughly, and keep everything organized. If you would like a second set of eyes on your photos, estimate, or denial letter, Dallas Public Adjuster serves Dallas, Dallas County, and surrounding North Texas communities. Request a free claim review and we can talk through where your claim stands. For legal questions, talk with a Texas attorney.
Frequently Asked Questions
How soon should I document hail damage after a storm?
As soon as it is safe, ideally within a day or two and before any repairs. Fresh damage is easier to see and easier to connect to a specific storm date. Hailstones melt within minutes to hours, so photograph them with a ruler or coin right away if you can.
Do I have to climb on my roof to document hail damage?
No, and you should not if the roof is wet, steep, two stories up, or damaged. Document gutters, vents, siding, windows, screens, and the AC unit from the ground, use zoom from a safe spot, and let a qualified roofer or adjuster document the roof surface.
How do I show the damage came from hail and not age or wear?
Combine close-up photos with a scale reference, matching dents on soft metals such as gutters, vents, and AC fins, your written notes on the storm date, and NOAA or National Weather Service reports for your area. Older photos showing the roof in good condition before the storm also help.
Should I make repairs before the insurance adjuster inspects?
Only temporary repairs that prevent further damage, such as tarping a roof or boarding a broken window. Photograph the damage before and after, keep receipts, and hold off on permanent repairs until the insurer has had a reasonable chance to inspect.
What if I find more damage after I file the claim?
Document it the same way and report it to your insurer in writing promptly. Additional damage found later, including during repairs, is often added to a claim through a supplement. Check your policy for any time limits on reporting.
Is hail damage to my car part of the same claim?
Usually not. Vehicle hail damage is typically handled under the comprehensive coverage of your auto policy, which is a separate claim from your homeowners or commercial property policy. The same documentation habits apply.
Sources and further reading
This article is general information about property insurance claims in Texas, not legal advice, and not a promise of any coverage or outcome. Your policy language and the facts of your loss control your claim.