
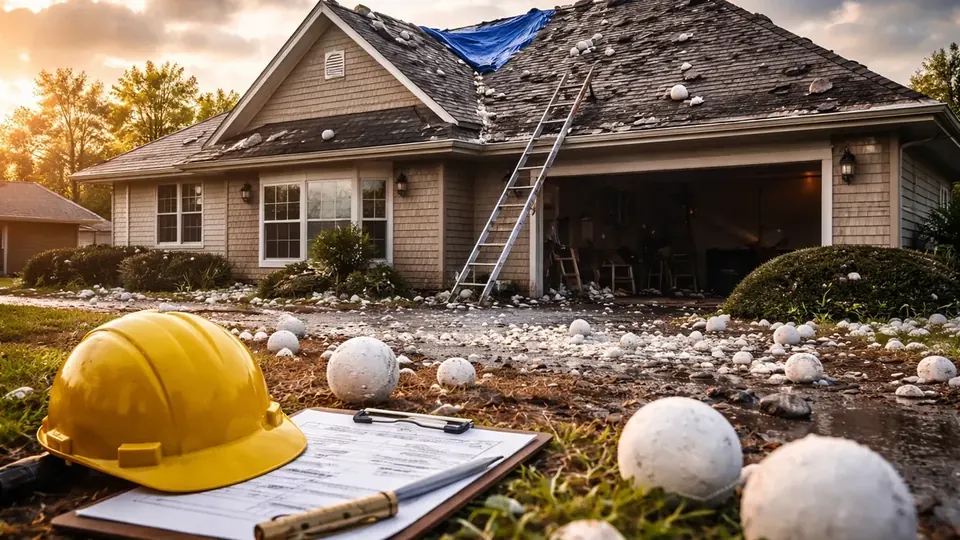
Dallas hail damage claims are among the most common property insurance claims in North Texas, and the weather record shows why. The NOAA Storm Events Database lists 841 hail reports in Dallas County since 1955. Of those, 250 were golf-ball size (1.75 inches) or larger and 46 were baseball size (2.75 inches) or larger. Reports pile up from March through June, peak in April and May, and show a smaller second bump in October.
Hail damage is often harder to spot than people expect. Bruised shingles, fractured mats, and dented flashing usually cannot be seen from the driveway. The full scope may only show up during a close, slope-by-slope roof inspection. This page explains what a hail claim usually involves, where disputes tend to start, and how a public adjuster in Dallas may help. For the numbers behind hail season, read Dallas hail season storm data.
Notable Hailstorms in Dallas County
A few storms from the NOAA record show how much damage hail can do here in a single afternoon:
- May 24, 2011. Grapefruit-size hail, 4.25 inches, fell in Irving, breaking windows and damaging property at the Four Seasons Las Colinas during the Byron Nelson tournament (NCEI event). The same storm dropped 2.75-inch hail near Skillman Street and Southwestern Boulevard, and golf-ball hail near Highway 183 and Mockingbird Lane damaged eight Southwest planes at Love Field.
- June 12, 2023. Hail up to 4 inches was reported near Cedar Hill (NCEI event), with 2.75-inch stones near Cedar Hill State Park.
- June 6, 2018. Three-inch hail hit Carrollton and Coppell (NCEI event).
- April 25, 2026. Three-inch hail near Dallas Baptist University blew out car windows (NCEI event).
Busy years can bring dozens of reports. NOAA logged 53 hail reports in the county in 2012, 52 in 2011, and 51 in 2023. When a property may have been hit more than once, insurers often ask which storm caused the damage, so dating the loss is one of the first things to get right.
What Hail Damages on Dallas Properties
Hail is a named peril on most homeowners and commercial property policies, subject to deductibles, exclusions, and endorsements. Claims here commonly involve:
- Roofs. Composition shingles on brick-veneer homes (granule loss, bruising, cracked mats), plus metal, tile, and slate on some houses, and TPO or modified-bitumen membranes on flat and low-slope commercial roofs. See our roof damage insurance claims page.
- Windows and skylights. Broken glass, cracked frames, and shredded screens.
- Siding and trim. Split or dented siding, chipped paint, damaged fascia and soffits. Brick usually holds up, but wood trim, window wraps, and sealants around it may not.
- Soft metals and equipment. Gutters, downspouts, roof vents, flashing, and the condenser coil fins on AC units.
- Other structures. Fences, sheds, pergolas, and detached garages.
- Interior water damage from broken windows or punctured roofing, usually handled as part of the same claim.
Documentation That Supports a Dallas Hail Claim
Good documentation ties the damage to a specific storm and shows the full scope of repairs. Our claim documentation checklist walks through this step by step.
| Document | Why it matters |
|---|---|
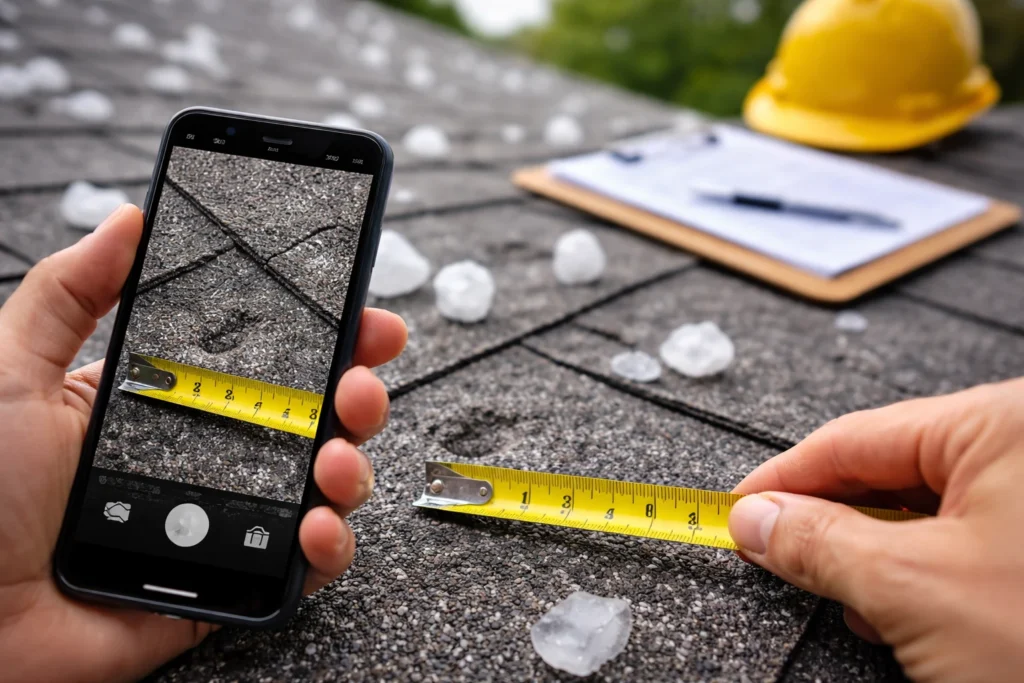
| Date-stamped photos and video | Shows hail size, roof condition, and damage before tarping or repairs. |
| Weather records (NOAA, NWS) | Helps confirm hail fell at or near the property on the date of loss. |
| Roof inspection with test squares | Records hits per square, mat fractures, and functional damage on each slope. |
| Itemized repair estimate | Line-item scope (often in Xactimate) for roofing, gutters, windows, and interior work. |
| Policy and declarations page | Confirms deductibles, roof payment schedules, and cosmetic damage endorsements. |
| Receipts for emergency repairs | Supports reimbursement for tarping and other steps to prevent further damage. |
Common Insurer Positions on Hail Claims
- “Wear and tear, not hail.” The insurer attributes granule loss or cracking to age, blistering, or manufacturing issues. Long North Texas summers age shingles, which gives this argument traction.
- “Prior storm.” The carrier says the damage came from an earlier storm, one before the policy period, or one that was not reported promptly.
- “Cosmetic only.” Dents on metal roofing or soft metals are labeled cosmetic under an exclusion endorsement.
- Repair instead of replace. The estimate allows spot repairs even when brittle or discontinued shingles cannot be repaired or matched.
- Missing line items. Drip edge, starter course, ridge cap, flashing, permits, and code-required items are left off. Our insurance estimate review looks for these gaps.
If the claim was denied outright, see our denied insurance claims page for next steps.
Settlement Factors to Understand
- Wind/hail deductibles. Often a percentage of the dwelling limit, not a flat amount. Check your declarations page before you compare estimates.
- ACV vs. replacement cost. Under replacement cost coverage, insurers typically pay actual cash value first and release recoverable depreciation after repairs are finished, often within a deadline stated in the policy. Some Texas roof coverage is ACV-only or follows a roof payment schedule. See replacement cost vs. actual cash value in Texas.
- Code upgrades. Re-roofing in the city generally requires a permit through the City of Dallas Planning & Development Department, and suburbs such as Garland, Richardson, and Irving have their own permit offices. Code-required work is paid only if your policy includes ordinance or law coverage, up to its limit. See local building codes.
Personal property, other structures, and additional living expenses each have their own limits, so look at every coverage section, not only the dwelling limit.
How Dallas Public Adjuster Can Help
Dallas Public Adjuster is a public adjusting service of Rise Public Adjusting LLC, licensed by the Texas Department of Insurance (license #3356839). A licensed public adjuster represents the policyholder, not the insurance company. On a hail claim, that can include inspecting the roof and exterior, reviewing the policy, gathering weather data, preparing a detailed estimate, and communicating with the insurer’s adjuster. If the claim was already paid low, we can review it for an insurance claim supplement or discuss whether appraisal fits a disagreement over the amount of loss. We cannot guarantee a result. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
Your Responsibilities After a Hailstorm
- Give prompt notice to your insurer.
- Protect the property from further damage (tarp openings, board broken windows) and keep every receipt.
- Photograph damage before repairs and save samples of damaged materials when practical.
- Submit a proof of loss if requested, within the time your policy requires.
- Cooperate with inspections and reasonable requests for documents.
Be cautious with door-to-door roofers after a big storm, and read anything before you sign it. Many policies also set a contractual deadline to file suit. For legal questions about deadlines or a dispute with your insurer, consult a Texas attorney.
Frequently Asked Questions
How soon should I report hail damage in Dallas?
As soon as you discover it. Most policies require “prompt” notice, and some set a specific reporting window for wind and hail losses. Check the conditions section of your policy. Waiting also makes it harder to tie damage to one storm in a season that can bring several hail days.
How can I show which storm caused my hail damage?
Dated photos, NOAA Storm Events records, National Weather Service reports, and the pattern of dents on soft metals such as vents, gutters, and AC fins can all help connect damage to a date. Start with our storm lookup tool and the Dallas County storm history page.
Why is my hail deductible so much higher than my regular deductible?
Many Texas policies carry a separate wind/hail deductible written as a percentage of the dwelling (Coverage A) limit, such as 1% or 2%, instead of a flat dollar amount. Your declarations page shows how yours is calculated. Dallas County is outside the TWIA area, so wind and hail coverage usually comes from your regular insurer.
The insurer says my roof damage is cosmetic. What does that mean?
Some policies include an endorsement that excludes dents or marks that do not affect how a roof sheds water, most often on metal roofing. Whether damage is cosmetic or functional is a frequent dispute. Read your endorsements and ask for the specific policy language the insurer is relying on.
Will insurance pay for a full roof replacement after hail?
It depends on the extent of damage on each slope, whether the shingles can be repaired or matched, and your policy terms. Some losses support replacement; others are scoped as repairs. A detailed inspection and line-item estimate help show which applies.
Can a public adjuster guarantee a bigger hail settlement?
No. A public adjuster can help document the loss, review the insurer’s estimate, and present the claim, but no one can guarantee an outcome. Results depend on your policy and the facts of the loss.